
Starting a credit repair business can be a rewarding venture. It helps people improve their financial health while offering a chance to build a sustainable, recurring-revenue business. The credit repair industry is growing, driven by increasing awareness of credit scores and financial education. However, launching this business requires careful planning, legal compliance, and strategic marketing. This guide will walk you through the essential steps to establish a successful credit repair company, blending practical advice with insights from my own journey helping a friend navigate this industry. Whether you’re an entrepreneur or someone passionate about financial empowerment, this article will educate, demonstrate, and fascinate you with actionable steps.
Understanding the Credit Repair Industry Landscape
The credit repair industry helps consumers improve their credit scores by addressing inaccuracies on their credit reports. With millions of Americans facing challenges like identity theft or derogatory marks, the demand for credit repair services is high. According to the Consumer Financial Protection Bureau, approximately 20% of Americans have errors on their credit reports, creating a need for professional assistance and alternative options like no credit check loans.
To succeed, you must understand key players like credit bureaus, federal laws, and state regulations. My friend, Sarah, learned this when she started her credit repair business. She spent hours researching the Fair Credit Reporting Act to ensure compliance. Familiarizing yourself with the industry’s legal and operational framework is crucial. This knowledge builds trust with clients and protects your business from legal pitfalls.
Navigating Legal Requirements and Compliance
Starting a credit repair business involves strict adherence to federal and state laws. The Credit Repair Organizations Act and the Consumer Credit Protection Act set guidelines to protect consumers. For example, you cannot charge upfront fees before services are rendered. Additionally, state-specific laws, like the Texas Office of Consumer Credit Commissioner requirements, may mandate a surety bond or CSO registration.
Sarah faced challenges registering her business with the Texas Secretary of State. She needed a Certificate of Registration and professional liability insurance. Research your state’s Department of State or Attorney General’s office for specific rules. Non-compliance can lead to fines or business closure. Therefore, consult a legal expert or use resources like the Florida Department of State for guidance. This ensures your credit repair company operates legally and builds client trust.
Setting Up Your Business Entity Properly
Choosing the right business entity is a foundational step. Options like an LLC or corporation offer liability protection and tax benefits. Registering with the Secretary of State and obtaining a Federal Employer Identification Number are essential. Sarah chose an LLC for her credit repair business, which simplified tax filing and protected her personal assets.
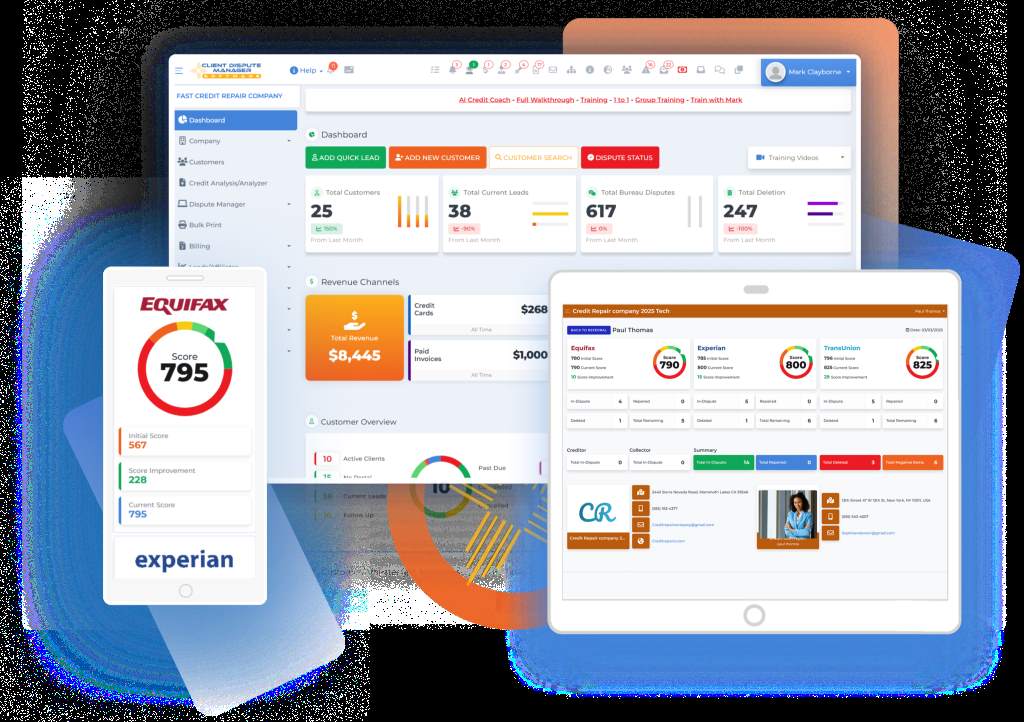
You’ll also need a Sales Tax ID if your state requires it. Consider professional liability insurance or cyber liability insurance to safeguard client data. Tools like Client Dispute Manager or Credit Repair Cloud can streamline operations. Setting up a solid business structure early saves time and reduces risks. Check with your state’s Department of State for specific registration steps to ensure compliance.
Developing a Strategic Business Plan
A well-crafted business plan is vital for success. It outlines your goals, target market, and financial projections. Focus on services like dispute letters, credit counseling, or financial education. Sarah’s business plan emphasized local businesses and referrals, which helped her attract clients. Include a section on marketing strategies, such as leveraging customer reviews or a referral program.
Your plan should also address cash flow and operational costs, like software subscriptions or certified consultants. According to the Accion Opportunity Fund, 82% of small businesses fail due to poor cash flow management. A detailed plan keeps your credit repair business on track and adaptable to industry changes.
Mastering Marketing Strategies for Growth
Effective marketing sets your credit repair business apart. Focus on building client relationships and trust through transparent services. Sarah used social media and local networking to promote her business, emphasizing client success stories. Consider offering on-demand courses or free financial education workshops to attract clients.
Optimize your website for SEO with keywords like “credit repair services” and “credit score improvement.” Avoid telemarketing tactics that violate the Telemarketing Sales Rule. Instead, use CRM systems to manage leads and nurture client relationships. Highlighting your expertise in areas like credit utilization ratio or FICO score improvements can draw clients seeking measurable results.
Leveraging Technology and Tools Effectively
Technology streamlines credit repair operations. Software like Credit Repair Cloud automates dispute letters and tracks client progress. Sarah invested in credit monitoring services to provide real-time updates to clients, boosting satisfaction. CRM systems help manage client data securely, which is critical given the sensitivity of credit reports.
Additionally, tools like Client Dispute Manager simplify workflows, allowing you to focus on client relationships. Ensure your systems comply with data protection laws to avoid issues with identity theft or breaches. Investing in reliable technology enhances efficiency and positions your business as professional and trustworthy.
Building Client Trust and Credibility
Trust is the cornerstone of a credit repair business. Clients share sensitive information, so transparency and ethical practices are non-negotiable. Offer clear contract requirements and avoid promising unrealistic results. Sarah built credibility by obtaining certifications from Money Management International and sharing client success stories (without breaching privacy).
Provide value through financial education or credit counseling. Explain terms like credit mix, payment history, or derogatory marks in simple language. Positive customer reviews and a referral program can amplify your reputation. Building trust ensures repeat business and word-of-mouth referrals, driving long-term success.
Avoiding Common Pitfalls and Mistakes
Starting a credit repair business has challenges. Common mistakes include ignoring state laws or neglecting bookkeeping practices. Sarah nearly faced penalties for overlooking California Civil Code requirements during an expansion. Always verify legal requirements with your state’s Attorney General or Department of State.
- Ignoring compliance: Failing to register as a Credit Services Organization can lead to fines.
- Poor client communication: Unclear expectations can harm client relationships.
- Overpromising results: Be honest about credit repair timelines to avoid disputes.
- Neglecting marketing: Without consistent promotion, client acquisition stalls.
Regularly review your business plan and seek advice from credit attorneys to stay compliant and competitive.
Scaling Your Credit Repair Business
Once established, scaling your business is the next step. Offer additional services like credit monitoring or business credit repair to diversify revenue. Sarah partnered with local businesses to offer credit repair as an employee benefit, boosting her client base. Consider hiring certified consultants to handle increased demand.
Explore partnerships with organizations like Mission Asset Fund for community outreach. A recurring-revenue business model, like subscription-based credit monitoring, ensures steady cash flow. Continuously refine your marketing strategies and invest in professional development to stay ahead in the evolving credit repair industry.
Your Path to a Thriving Credit Repair Business
Starting a credit repair business is both challenging and rewarding. By understanding the industry, complying with legal requirements, and leveraging technology, you can build a trusted brand. A solid business plan and effective marketing strategies will drive growth, while client trust ensures longevity. My friend Sarah’s journey taught me the value of persistence and compliance in this industry. Take the first step today—research your state’s regulations and start planning. Share your thoughts or experiences in the comments below, or spread this guide to inspire others!
FAQs
What is the Credit Repair Organizations Act?
This federal law regulates credit repair businesses, prohibiting upfront fees and mandating clear contract requirements.
Do I need a surety bond for my credit repair business?
Some states, like Texas, require a surety bond to register as a Credit Services Organization.
How can I market my credit repair services effectively?
Use SEO, social media, and referral programs while avoiding telemarketing to attract clients ethically.
What software is best for a credit repair business?
Credit Repair Cloud and Client Dispute Manager streamline dispute letters and client management.
Are there certifications for credit repair professionals?
Yes, organizations like Money Management International offer certifications to boost credibility.
References: