Starting a business requires capital. However, many entrepreneurs face a common challenge. They lack collateral or an established credit history. Fortunately, securing a business loan with only a solid business plan is possible. This approach requires preparation, strategy, and understanding what lenders look for.
Understanding Business Plan Loans
A business plan loan focuses on your concept rather than existing assets. Lenders evaluate your vision, market research, and financial projections. Therefore, your business plan becomes your most valuable tool. It demonstrates your commitment and ability to succeed.
Traditional loans often require collateral or personal guarantees. However, some lenders specialize in concept-based financing. These include the Small Business Administration (SBA), online lenders, and microfinance institutions. Additionally, some angel investors and venture capitalists consider strong business plans.
Creating a Compelling Business Plan
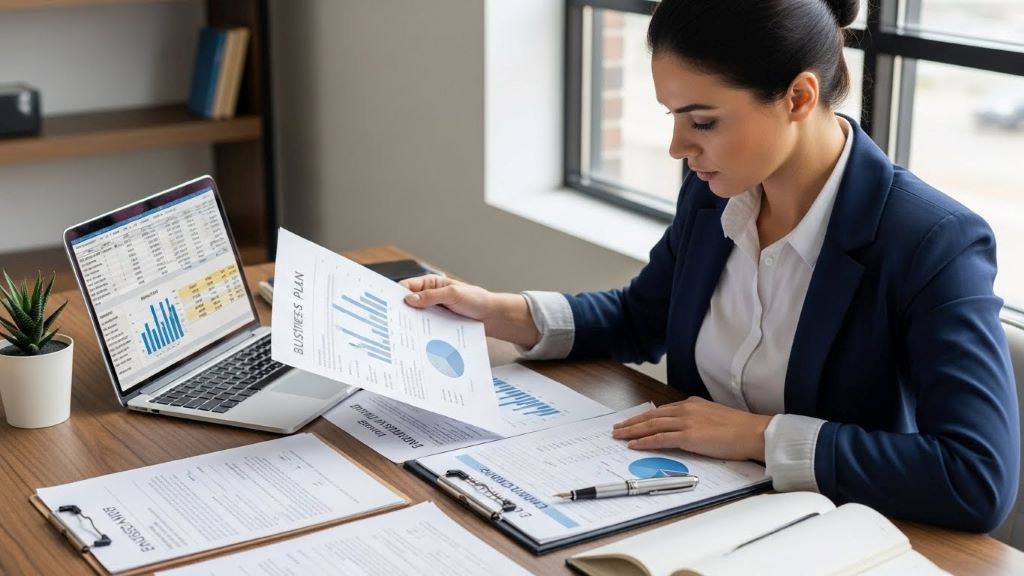
Your business plan must be comprehensive and professional. Start with an executive summary that captures attention immediately. This section should highlight your unique value proposition clearly. Make it concise yet powerful enough to engage potential lenders.
Next, include a detailed company description. Explain what your business does and why it matters. Furthermore, identify your target market and customer demographics. Lenders want to see that you understand your audience deeply.
The market analysis section proves you have done your homework. Research your industry thoroughly and present relevant data. Moreover, analyze your competition and explain your competitive advantage. Use statistics from reputable sources like the U.S. Small Business Administration to support your claims.
Your organizational structure should outline your management team. Highlight relevant experience and expertise of key personnel. Consequently, this builds confidence in your ability to execute the plan. If you are a solo entrepreneur, emphasize your skills and advisory board.
Developing Strong Financial Projections
Financial projections are critical when you lack collateral. Create realistic revenue forecasts for at least three years. Include projected income statements, cash flow statements, and balance sheets. Additionally, break down your startup costs in detail.
Be conservative in your estimates while showing growth potential. Lenders appreciate realistic assumptions over overly optimistic projections. Therefore, explain the logic behind every number you present. Include best-case and worst-case scenarios to demonstrate preparedness.
Your funding request should be specific and justified. State exactly how much money you need and why. Furthermore, explain how you will use every dollar of the loan. This transparency builds trust with potential lenders significantly.
Identifying the Right Lenders
Not all lenders accept business plan-only applications. Research institutions that specialize in startup financing carefully. The SBA offers several programs for new businesses without extensive collateral. Their microloan program is particularly suitable for small funding needs.
Online lenders have become increasingly popular alternatives. They often have more flexible requirements than traditional banks. However, interest rates may be higher due to increased risk. Compare multiple options before making your decision wisely.
Community development financial institutions (CDFIs) support underserved entrepreneurs. They focus on economic development rather than just profit. Moreover, they often provide business counseling alongside financing. Credit unions also offer more personalized service than large banks.
Strengthening Your Loan Application
Your personal credit score still matters even without collateral. Check your credit report and address any errors immediately. Additionally, pay down existing debts to improve your debt-to-income ratio. A score above 680 significantly increases your approval chances.
Prepare a professional presentation package beyond the written plan. Include supporting documents like licenses, permits, and contracts. Furthermore, gather letters of intent from potential customers or partners. These demonstrate market validation for your concept effectively.
Practice your pitch thoroughly before meeting with lenders. Be prepared to answer tough questions about your business. Moreover, show enthusiasm and confidence in your vision authentically. Your passion can compensate for lack of collateral sometimes.
Demonstrating Industry Knowledge
Lenders invest in people who understand their markets deeply. Stay current with industry trends and regulatory changes. Therefore, reference recent developments in your business plan appropriately. This shows you are serious and informed about your field.
Join industry associations and attend relevant networking events. These connections can provide valuable references for your application. Additionally, they demonstrate your commitment to professional growth continuously. Some associations even offer funding resources to members exclusively.
Consider obtaining relevant certifications or completing industry-specific training. These credentials enhance your credibility significantly with lenders. Furthermore, they show you are investing in your own success proactively.
Exploring Alternative Funding Sources
While pursuing traditional loans, consider complementary funding options. Crowdfunding platforms allow you to validate your concept publicly. Additionally, successful campaigns demonstrate market demand to potential lenders. According to Forbes, crowdfunding has helped thousands of entrepreneurs launch businesses successfully.
Grants represent non-repayable funding for specific business types. Research federal, state, and local grant opportunities thoroughly. However, competition is fierce and applications require significant effort. Nevertheless, grants do not require repayment or equity surrender.
Business plan competitions offer cash prizes and valuable exposure. Many universities, corporations, and organizations sponsor these events regularly. Moreover, winning provides credibility that strengthens future loan applications remarkably.
Negotiating Loan Terms
Once approved, carefully review all loan terms before signing. Understand the interest rate, repayment schedule, and any fees involved. Additionally, clarify prepayment penalties and default consequences explicitly. Never hesitate to ask questions about unclear terms.
Negotiate when possible, especially with smaller lenders or CDFIs. You might secure better terms by offering to accept business counseling. Furthermore, consider offering a personal guarantee as a compromise option. This shows commitment while avoiding traditional collateral requirements.
Request the longest repayment period your lender offers reasonably. This reduces monthly payments and improves cash flow management. However, remember that longer terms mean paying more interest overall. Balance affordability with total cost when making this decision.
Building Lender Relationships
Establishing relationships with lenders before needing money is smart strategy. Open a business checking account at your target bank early. Additionally, maintain consistent deposits and responsible account management always. This creates a positive financial history with the institution.
Schedule informational meetings with loan officers before applying formally. Ask about their lending criteria and preferred documentation styles. Moreover, request feedback on your preliminary business plan draft. This demonstrates professionalism and helps you tailor your application effectively.
Stay in touch with lenders even after receiving funding. Provide periodic updates on your business progress and milestones. Furthermore, timely loan repayments build your credibility for future financing needs. These relationships become invaluable assets for business growth longterm.
Conclusion
Securing a business loan with only a business plan is challenging but achievable. Success requires a comprehensive, realistic plan backed by thorough research. Additionally, choosing the right lenders and presenting yourself professionally matters greatly. Your personal credibility, industry knowledge, and financial projections must convince lenders of your potential.
Start by creating a detailed business plan with strong financial projections. Research lenders who specialize in concept-based financing carefully. Furthermore, strengthen your application with supporting documents and industry credentials. Consider alternative funding sources to complement traditional loans strategically.
Remember that persistence often leads to success in business financing. Rejection from one lender does not mean your plan is flawed. Therefore, continue refining your approach and exploring different options diligently. With dedication and preparation, you can secure the funding needed to launch your entrepreneurial dreams successfully.
Frequently Asked Questions
Can I get a business loan with bad credit and no collateral?
Getting approved is more difficult but not impossible with poor credit. Focus on lenders like CDFIs or microloan programs that emphasize business potential. Additionally, consider bringing on a creditworthy co-signer or improving your credit score before applying.
How detailed should my financial projections be?
Your projections should include monthly forecasts for the first year and quarterly projections for years two and three. Include all three major financial statements with clear assumptions. Moreover, explain how you calculated each projection to demonstrate realistic thinking.
What is the minimum credit score needed for a business plan loan?
Most lenders prefer scores above 680, though some accept scores as low as 600. The SBA microloan program may work with lower scores if other factors are strong. However, higher scores always improve your chances and may secure better interest rates.
How long does the loan approval process typically take?
Traditional bank loans may take four to six weeks or longer for approval. Online lenders often provide decisions within days and funding within weeks. However, SBA loans can take several months due to additional documentation requirements and processing procedures.
Should I apply to multiple lenders simultaneously?
Yes, applying to several lenders increases your approval chances without harming your credit significantly. Multiple inquiries within a short period typically count as one inquiry. However, avoid applying to too many lenders as this may signal desperation to financial institutions.
Related Topics:
Common Entrepreneurial Mistakes and How to Avoid Them
The Startup Mindset: How to Stay Resilient in Tough Times