
The dream of homeownership often feels out of reach due to high interest rates and soaring property prices. Yet, over 60 percent of homebuyers in 2024 secured mortgages with interest rates below 4 percent through assumption agreements. Taking over a low interest mortgage can save you thousands in the long run and provide stability in an unpredictable market.
Understanding Mortgage Assumptions
A mortgage assumption is a process where a buyer takes over the seller’s existing mortgage loan. This means the buyer adopts the remaining balance, interest rate, and repayment terms of the original loan. Not all mortgages are assumable, so it is important to check the loan type first.
Government-backed loans such as FHA, VA, and USDA loans are typically assumable. Conventional loans may also be assumable, but this is less common and often requires lender approval. The primary benefit of assuming a mortgage is the ability to secure a lower interest rate than what is currently available.
For example, if the seller has a VA loan at 3 percent interest and current rates are at 6 percent, assuming the loan can save you a significant amount over the life of the mortgage. This can be particularly advantageous for entrepreneurs looking to use data driven marketing hacks to grow their business.
Benefits of Taking Over a Low Interest Mortgage
The most obvious benefit is the potential for substantial savings. With a lower interest rate, your monthly payments will be reduced, and you will pay less interest over the life of the loan. This can free up cash flow for other investments or expenses.
Assuming a mortgage can also simplify the home buying process. Since you are taking over an existing loan, you may avoid some of the closing costs and fees associated with a new mortgage. Additionally, the process can be faster than applying for a new loan.
Another advantage is the ability to bypass stricter lending standards. If you have a lower credit score or higher debt-to-income ratio, assuming a mortgage might be easier than qualifying for a new loan. This can be a game changer for those looking to compete with retail giants in competitive markets.
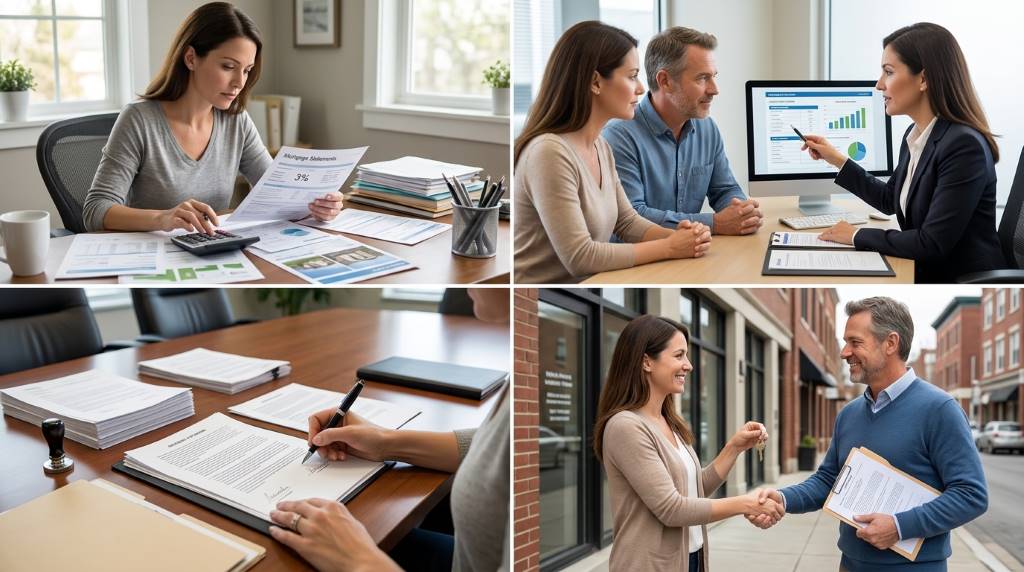
Step-by-Step Process to Take Over a Low Interest Mortgage
Step 1: Verify Loan Assumability
The first step is to confirm that the existing mortgage is assumable. Review the loan documents or ask the seller to provide this information. Government-backed loans like FHA, VA, and USDA loans are usually assumable, but conventional loans may have restrictions.
Contact the lender to verify the assumability of the loan. They can provide the necessary details and guide you through their specific process. It is important to get written confirmation that the loan can be assumed.
Step 2: Review the Mortgage Terms
Once you confirm the loan is assumable, review the terms carefully. Look at the interest rate, remaining balance, repayment period, and any other conditions. Ensure that the terms align with your financial goals and capabilities.
Pay attention to any clauses that might affect the assumption, such as due-on-sale clauses, which require the loan to be paid in full if the property is sold. If such a clause exists, the lender’s approval will be necessary to proceed.
Step 3: Qualify for the Assumption
Even though you are taking over an existing loan, you will still need to qualify for the assumption. The lender will review your credit score, income, debt-to-income ratio, and other financial factors to ensure you can make the payments.
Prepare the necessary documents, such as proof of income, credit reports, and employment history. The lender may have specific requirements, so ask for a list of what you need to provide.
Step 4: Submit an Assumption Application
Work with the lender to complete the assumption application. This process is similar to applying for a new mortgage but may be simpler since the loan terms are already established.
The lender will process your application and may charge a fee for the assumption. Be prepared to pay any required fees, which can vary depending on the lender and loan type.
Step 5: Close the Assumption
Once approved, you will need to close the assumption. This involves signing the necessary paperwork to transfer the loan into your name. The seller will also need to sign documents releasing their liability for the loan.
At closing, you will pay any required fees and receive the keys to the property. The lender will provide a new payment schedule and other relevant details.
Unique Considerations for Low Interest Mortgage Takeovers
One uncommon but highly effective strategy is to negotiate a seller carryback mortgage. In this scenario, the seller finances part of the purchase price, allowing you to take over the existing low interest mortgage and cover the remaining balance with a second loan from the seller.
This approach can be particularly useful if the purchase price exceeds the remaining balance on the assumable mortgage. For example, if the home is valued at 300,000 USD but the remaining mortgage balance is 200,000 USD, the seller could carry back a second mortgage for the 100,000 USD difference at a mutually agreed upon interest rate.
Another unique consideration is the impact of local market conditions. In areas with high demand and limited inventory, sellers may be more open to creative financing options, including mortgage assumptions. For those in niche markets like home based food entrepreneurs, securing a low interest mortgage can provide the financial stability needed to grow their business.
It is also important to consider the long-term implications of assuming a mortgage. While the immediate benefits are clear, think about how this decision fits into your broader financial plan. For instance, if you plan to sell the property in a few years, ensure that the assumption process will not complicate that transaction.
Potential Challenges and How to Overcome Them
One of the main challenges is finding a property with an assumable mortgage. Not all sellers are aware that their loan can be assumed, and not all loans are eligible. Working with a real estate agent who understands creative financing can help you identify suitable properties.
Another challenge is meeting the lender’s qualification criteria. If your credit score or income does not meet the lender’s standards, you may struggle to get approval. In such cases, consider improving your financial profile before applying or exploring other financing options.
Additionally, some lenders may require a down payment or other upfront costs, even for an assumption. Be prepared for these expenses and factor them into your budget.
Real-Life Example: Taking Over a Low Interest Mortgage
Consider the case of John, a first-time homebuyer in a competitive housing market. John found a home with an existing FHA loan at a 3.5 percent interest rate, significantly lower than the current market rate of 6 percent.
John worked with the seller and lender to verify the loan’s assumability and submitted his application. After qualifying, he closed on the assumption, taking over the existing mortgage and saving over 200 USD per month compared to a new loan at current rates.
Over the life of the 30-year mortgage, John will save tens of thousands of dollars in interest payments. This financial flexibility allowed him to invest in other opportunities, such as starting a side business.
Tips for a Smooth Mortgage Assumption Process
Start by educating yourself on the types of loans that are assumable and the specific requirements for each. This knowledge will help you identify suitable properties and navigate the process more effectively.
Work with professionals who have experience with mortgage assumptions. A real estate agent, mortgage broker, or attorney can provide valuable guidance and help you avoid common pitfalls.
Be proactive in gathering the necessary documents and information. The faster you can provide what the lender needs, the smoother the process will be.
Finally, communicate openly with the seller and lender. Clear communication can help resolve any issues quickly and keep the process on track.
Conclusion
Taking over a low interest mortgage can be a smart financial move, offering significant savings and a simpler home buying process. By understanding the steps involved, considering unique strategies, and preparing for potential challenges, you can successfully assume a mortgage and enjoy the benefits of lower interest rates.
If you are ready to explore this option, start by identifying properties with assumable mortgages and consulting with professionals who can guide you through the process. With the right approach, you can secure a low interest mortgage and take a major step toward achieving your homeownership goals.
Do not let high interest rates hold you back from buying the home of your dreams. Take action today and explore the possibility of assuming a low interest mortgage.
Frequently Asked Questions
What types of mortgages are assumable?
Government-backed loans like FHA, VA, and USDA loans are typically assumable, while conventional loans may require lender approval.
Do I need to qualify for a mortgage assumption?
Yes, you will need to meet the lender’s qualification criteria, including credit score, income, and debt-to-income ratio.
Can I assume a mortgage with a due-on-sale clause?
You may assume a mortgage with a due-on-sale clause if the lender approves the assumption.
Are there fees associated with assuming a mortgage?
Yes, lenders may charge assumption fees, which can vary depending on the loan type and lender.
How can I find properties with assumable mortgages?
Work with a real estate agent who understands creative financing and can help you identify suitable properties.