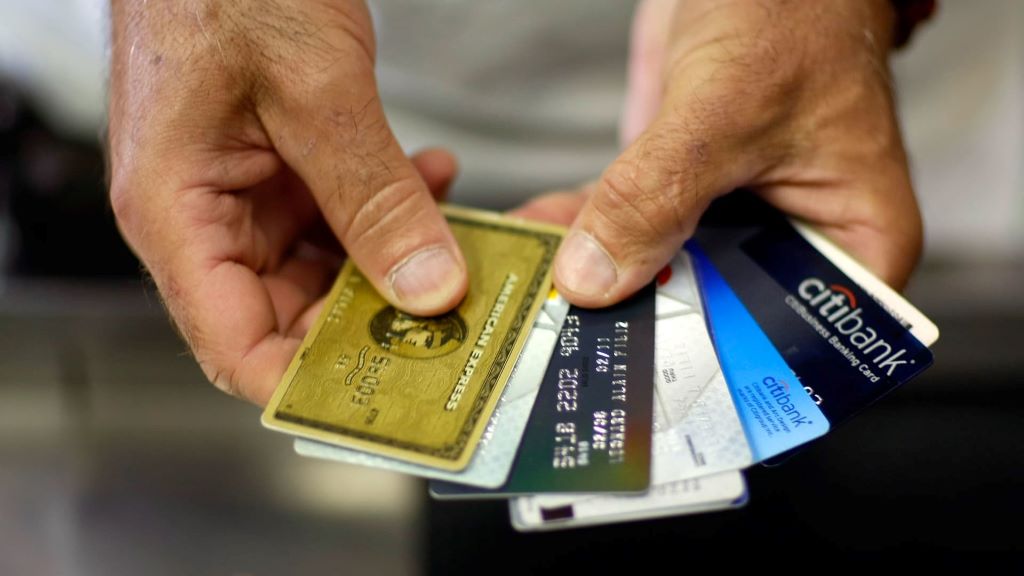
In today’s competitive market, securing the right business credit card can become a game-changer for your company’s growth. These cards offer more than just a line of credit—they provide opportunities to optimize cash flow, earn valuable rewards, and streamline expenses. However, not all business credit cards are created equal. Choosing the right card requires understanding your company’s unique financial needs and growth objectives.
Why Business Credit Cards Matter for Growth
A recent survey by Nav revealed that 82% of small business owners use credit cards to manage their cash flow and cover unexpected expenses. This statistic highlights how essential credit cards have become in bridging gaps during growth phases. Moreover, business credit cards often come with rewards tailored for company spending, such as travel points, cashback on office supplies, and discounts on software subscriptions.
When used strategically, these rewards can significantly reduce operating costs and improve profitability. For example, the American Express Business Gold Card offers 4X points on the top two categories where your business spends the most. For companies with varied expenses, such flexibility can translate to thousands in savings annually.
Top Picks for Business Credit Cards That Fuel Growth
-
Chase Ink Business Preferred Credit Card
Chase Ink Business Preferred is a favorite for many entrepreneurs due to its generous sign-up bonus and 3X points on the first $150,000 spent annually in select business categories. This card suits businesses with high travel or advertising expenses, as those categories earn more points. Additionally, points can be transferred to various travel partners, giving business owners flexibility. Chase’s extensive acceptance and strong security features further boost its appeal.
-
American Express Blue Business Cash™ Card
This card stands out for companies seeking straightforward cashback without annual fees. It offers 2% cashback on all purchases up to $50,000 per year, which is excellent for everyday business expenses. Small and medium-sized enterprises that want to keep costs low while gaining steady rewards will find this card practical. The purchase protection and expense management tools also simplify financial tracking.
-
Capital One Spark Cash Plus
If your business has high monthly expenses, the Capital One Spark Cash Plus card is worth considering. It offers an unlimited 2% cashback on every purchase, no caps, which is ideal for businesses with substantial recurring costs. Additionally, it features no preset spending limit, accommodating scaling companies that may face fluctuating expenditures. While the annual fee is higher, the unlimited cashback compensates well.
Factors to Consider When Choosing a Business Credit Card
Selecting the right card isn’t just about rewards. Companies must weigh the following:
- Annual Fees vs. Benefits: A high annual fee might be justified if the rewards or perks exceed that cost.
- Interest Rates: For businesses that carry balances, low APRs can save money on interest.
- Credit Limits: Growth-focused companies need cards with high limits or flexible spending options.
- Expense Management Tools: Features like detailed reporting and employee card controls can streamline bookkeeping.
- Sign-Up Bonuses: A large introductory bonus can provide a quick financial boost.
Logic dictates that aligning the card’s strengths with business spending habits maximizes value. For instance, a company with frequent travel expenses benefits more from cards offering travel rewards rather than flat cashback.
Real-World Business Impact
Consider a tech startup spending heavily on cloud services and software subscriptions. A card like the Chase Ink Business Preferred, which awards bonus points on advertising and internet services, helps reduce net expenses. According to Forbes, savvy business owners can leverage these rewards to invest back into growth initiatives, effectively turning expenses into strategic funding.
Another example comes from retail businesses, where cash flow is crucial. The American Express Blue Business Cash card helps maintain liquidity with its straightforward cashback system, freeing capital for inventory and marketing. This kind of practical financial tool supports business agility—a critical factor in scaling operations.
Professional Tips for Using Business Credit Cards Effectively
- Separate Personal and Business Expenses: Avoid confusion and maintain clean accounting by using business cards exclusively for company expenses.
- Pay Balances in Full: To maximize rewards, avoid interest charges by paying off monthly balances completely.
- Leverage Employee Cards: Distribute cards with set limits to key employees to simplify expense tracking and reduce fraud risk.
- Review Statements Monthly: Regular checks help catch unauthorized charges early and provide insights into spending patterns.
- Negotiate Credit Limits: Don’t hesitate to ask for higher limits as your business grows to maintain flexibility.
Featured Snippet: What Are the Best Business Credit Cards to Boost Company Growth?
The best business credit cards to boost your company’s growth combine valuable rewards, low fees, and useful financial tools. Cards like Chase Ink Business Preferred offer high points on key business expenses, while American Express Blue Business Cash provides simple cashback with no annual fees. For companies with large expenses, Capital One Spark Cash Plus offers unlimited cashback and no preset spending limits. Using these cards strategically improves cash flow, cuts costs, and supports reinvestment into business growth. Always match your card choice to your unique spending profile for maximum benefits.
Frequently Asked Questions (FAQs)
-
Can business credit cards help build company credit?
Yes, timely payments and responsible use improve your business credit score, aiding future financing options.
-
Are business credit cards different from personal cards?
Yes, they offer tailored rewards, higher credit limits, and tools for managing multiple employees’ spending.
-
What is a good credit limit for a growing business?
It depends on expenses, but limits above $10,000 typically provide flexibility for scaling companies.
-
Do business credit cards offer liability protection?
Most provide protection against fraudulent charges, similar to personal credit cards.
-
Are rewards from business credit cards taxable?
Usually, rewards are not taxable unless received as cash or bonuses beyond regular spending rewards.
-
Can startups qualify for top business credit cards?
Yes, many cards consider personal credit history and business potential during approval.
-
How often should businesses review their credit card options?
At least annually, to ensure the card aligns with changing spending habits and company growth.
Final Thought
Choosing from the top business credit cards to boost your company’s growth isn’t just about perks—it’s a strategic decision that impacts cash flow, expense management, and future scalability. Carefully analyzing your spending patterns and business needs helps you unlock the best financial tools. Whether it’s earning rewards on travel, getting cashback on everyday expenses, or enjoying flexible credit limits, the right card acts as a powerful ally in your business journey.
Read More: The Best Lending Platforms for Small Business Owners